
How mortgage advice has changed: From the eyes of a veteran
After being in the mortgage game for nearly a decade, Mikey Smith, founder of Guardian Smith, says he has seen big transition in clients’ knowledge.
Monday, August 31st 2026, 6:10AM
by Sally Lindsay
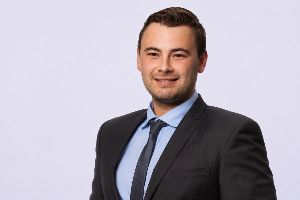
Starting the mortgage, insurance and KiwiSaver advisory business in 2022, it now has 60 advisers across New Zealand demystifying financial advice, making it accessible and client-first.
As financial and insurance advice has evolved, Smith says clients now know they need to have their “ducks in a row” before buying a house.
“A decade ago, we would get calls like: ‘Hey, I have just won this auction. Can you sort the loan, please?’.”
Smith says it was wild times, particularly when lending regulations changed under the CCCFA and banks started requiring property insurance before signing off on a mortgage.
Both lending and insurance have changed so much, and this has flowed downstream to the point where clients realise they need to talk to an adviser.
“There was a dicey transition period for a while as behaviour had to be adjusted. Nowadays, the majority of clients know that preparation is key.”
Although mortgage advisers are called just that, they need to have a service mentality, Smith says. “If a client calls and says they want to buy a house, what they are really saying is ‘get me the mortgage approval, provide me with some advice around what it is going to cost and I need to know the process inside out in terms of insurance and making sure the bank likes the property’.
“The stack of things clients have to go through to actually buy a home is now so big, they want somebody else to put it all together.”
The second major behaviour change he has noticed is advisers can no longer get away with being transactional.
Regardless of the transaction, clients want information and education. The best meetings advisers can have revolve around the bigger picture – not just the next 12 minutes, 12 weeks or 12 months, Smith says.
“They want the full platter – to understand the ins and outs of the process and picture of what their finances will look like well into the future – making sure their goals are front and centre.”
In Smith’s opinion the client narrative for too long has been “we don’t know what we are doing”.
“That’s changing. Access to information and advice is working and people are becoming more aware of their finances, budgeting, the numbers, and as a result are making better decisions.”
His one word of advice, after the frenzy of pundits a few years ago claiming people could not save for a house deposit while they were eating avocado on toast at $22 a time in cafes, is subscriptions and their horror stories.
“Subscriptions are the silent financial killer nowadays,” Smith says.
Research shows one in five Kiwis are paying for subscriptions they don’t use. A third of New Zealanders spend more than $100 a month on subscriptions — money that could be going toward saving, investing, or simply easing a tight household budget.
Smith says it’s not always about the big financial levers – it’s about trimming back on the little expenses that can quietly snowball.
New Zealand banks and lenders review regular expenses on bank statements. Small recurring fees lower a client’s disposable income on paper, which can reduce how much they can borrow for a mortgage.
He says advisers should be stepping up warnings to clients about the common pitfalls of free trials that auto-renew and start charging without warning, annual billing cycles where a client forgets until a large bill arrives, and confusing cancellation processes designed to wear people down.
Westpac became so concerned about “subscription traps” it introduced a payment block on some merchants.
Since introducing the payment block in April 2024, it has helped prevent more than $25 million in unwanted charges to more than 20,000 of its customers.
The block only applies to businesses who mislead customers and then make it extremely difficult to cancel recurring payments.
These types of businesses aren’t necessarily acting fraudulently, because they do disclose the subscription details in their fine print, but typically they don’t offer this information up front, the bank says.
As a result, it views their money-making model as unethical.
| « OCR Up: What the RBNZ said | NZFSG calls out banks for chasing advisers' clients » |
Special Offers
Comments from our readers
No comments yet
Sign In to add your comment
|
|
Printable version |
|
Email to a friend |