
Diversifying doesn’t mean more cost
Mortgage advisers don’t need to spend thousands of dollars on AI and advertising to run a successful business, Mikey Smith, Guardian Smith founder says
Tuesday, September 29th 2026, 3:35PM  2 Comments
by Sally Lindsay
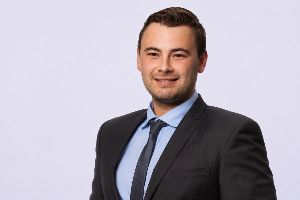
After a stint as car rental business owner, Smith came into the sector firstly as a NZFSG salaried mortgage adviser before setting up his own business, which now has 60 advisers nationwide giving advice on mortgages, insurance and KiwiSaver.
He says while the country has been in a three year recession and mortgage advice activity has not been at the same level as in the past decade, the reality is if an adviser has a good name and puts in the effort to do an outstanding job, it is possible to run a successful business.
“Many advisers are overly attracted to lead generation, and marketing using AI and can spend $15,000, for example, to run some Facebook advertisements when they could be more creative.
“They could run a webinar, produce a newsletter, or explore the many different and cheaper ways to introduce themselves to people. I remember knocking on doors. Nobody does it anymore, but it still works.”
Smith says referral partners are also a hugely successful way to generate successful business – real estate agents, accountants, lawyers, financial planners and others.
“Too many advisers think by putting thousands of dollars into Facebook it will bring in a lot of business, but it doesn’t really work like that.”
NZFSG says finding new clients is often the toughest part of running an advice business, so it’s vital to make every interaction worthwhile. The aggregator says in the highly regulated sector it’s challenging for advisers to offer every type of service.
This is where referral partners become invaluable. Mortgage and insurance referrals are now well established in the industry, though NZFSG says far too many advisers are missing out on the potential from general insurance and KiwiSaver.
Despite that, a growing number of advisers within its network have built significant financial safety nets for their businesses through strong recurring income from referrals.
Advisers broadening their service, are not just meeting more of a client’s needs, they’re building trail income that continues to pay long after the initial deal, NZFSG says.
When an adviser wants to sell their business, recurring revenue is often the biggest factor in determining value. Many advice firms are now being valued at two to four times their annual trail income.
Smith went into the industry a decade ago “full of will but no skill”.
“I went away and became like a dog with a bone about it. Not knowing what you are doing some of the time is just a natural feeling, but you have to trust that if you work hard, do a good job, are nice to people, act honestly and with integrity you will do well.”
One of the big questions facing mortgage advisers is whether open banking will lead to a proliferation of online only mortgage platforms offering transactions but no advice and cut their client numbers.
Smith believes there will be more platforms along the lines of Dosh, which offers Westpac mortgages direct to people using its site.
“They are great for convenience; however, they will never replace human advisers. When clients come to us, they have goals to meet and we run through the process, the costs and whether the advice is aligned with their long-term plans.
“That is never going to happen with an online provider or an AI tool. If somebody doesn’t qualify for a mortgage when they have inquired through an online platform that is the end of the engagement.
“Human advisers don’t say see you later. They say here are the next steps, we will talk to you again in six months and if you have followed our advice, you will get a mortgage.”
For advisers it is turning every person who phones or comes through the door into a long-term client by providing value to them no matter what stage they are at.
“Regardless of what is happening with AI or online platforms, advisers have much more room to run a successful business with creativity and thinking differently about how that can happen,” Smith says.
| « Growth at Link points to adviser channel opportunities | Vale Josh Bronkhorst » |
Special Offers
Comments from our readers
The Financial Markets Authority (FMA) requires strict transparency around all insurance commission payments. Advisers are legally obligated to disclose any potential conflicts of interest, including the exact referral fees and commission cuts shared between the adviser, the aggregator, and any third-party partners. Advisers having their own private referral agreement with an insurance adviser who specialises in Fire and General insurance makes more sense then than relying on an aggregator’s scheme.
Sign In to add your comment
|
|
Printable version |
|
Email to a friend |


These aggregator referral arrangements see the insurer making payment to the aggregator first who then passes along the adviser’s commission to them.
If the adviser later decides to move to a different aggregator (which is happening a lot currently) the insurer will continue paying the original aggregator for those policies already in force. The aggregator may then charge the adviser a monthly service fee for simply passing along their commission to them or keep the commission for themselves.
With the above in mind, it’s much better for mortgage advisers to have their own referral arrangements directly with a local general insurance adviser themselves aka no aggregator involvement, the clients premium maybe cheaper.